Our Latest Insights

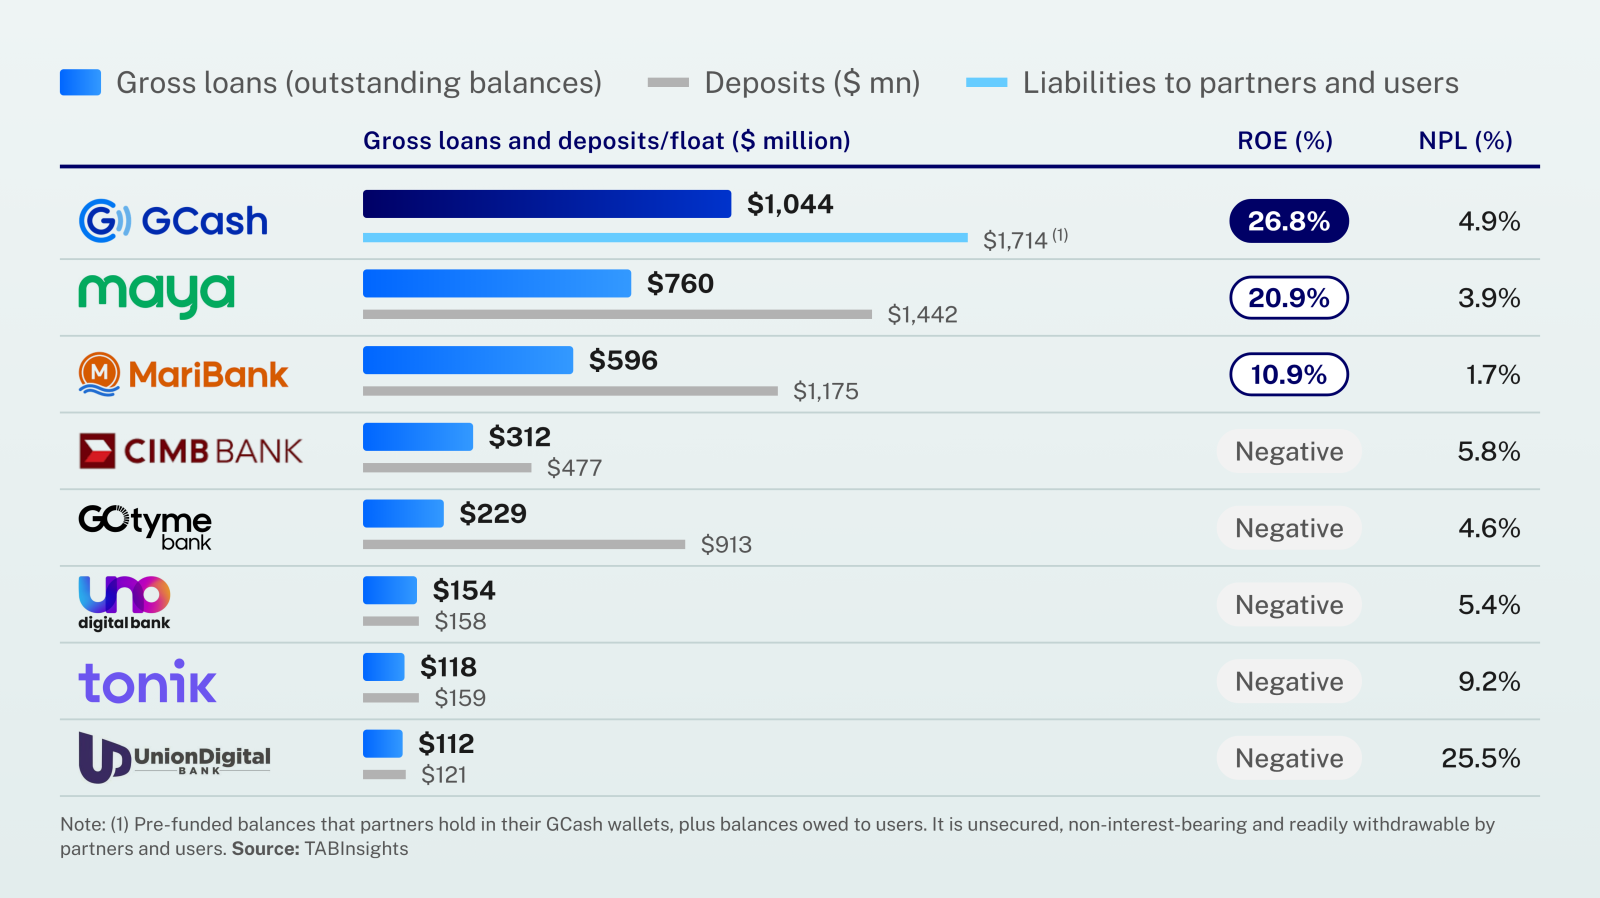
GCash has evolved from a payments platform into a bank-like lender, with a loan book and profitability exceeding those of the Philippines’ licensed digital banks. Lending now drives growth, but rising credit losses pose a growing challenge to profitability. Without a bank’s deposit base or banking regulatory framework, GCash’s model combines competitive advantages with structural risks.
Rankings Oct 26

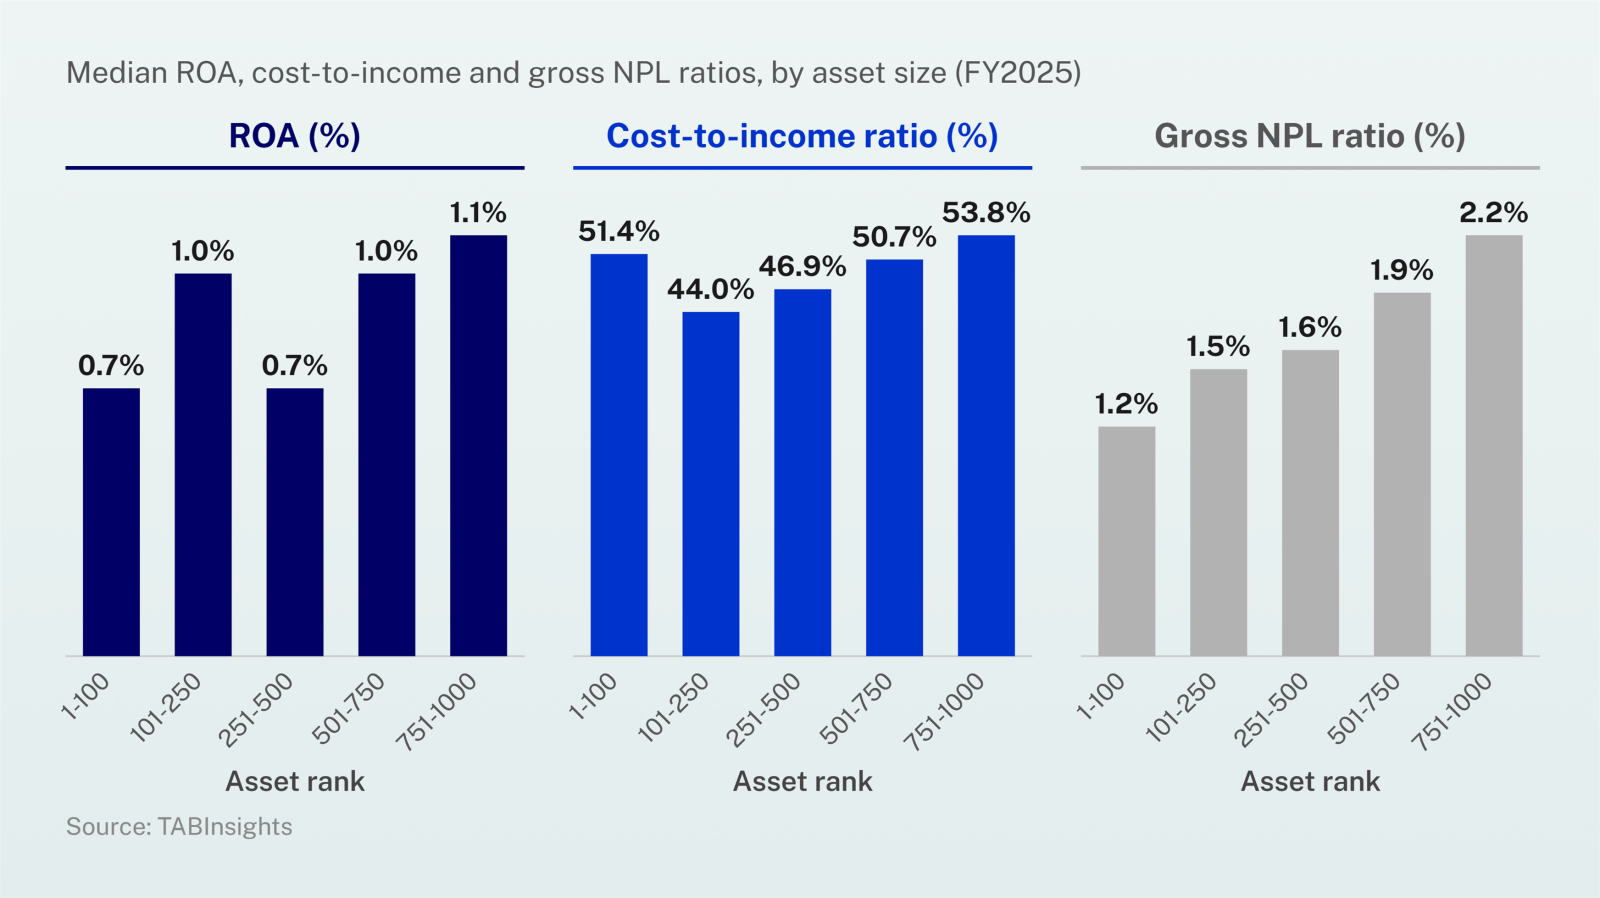
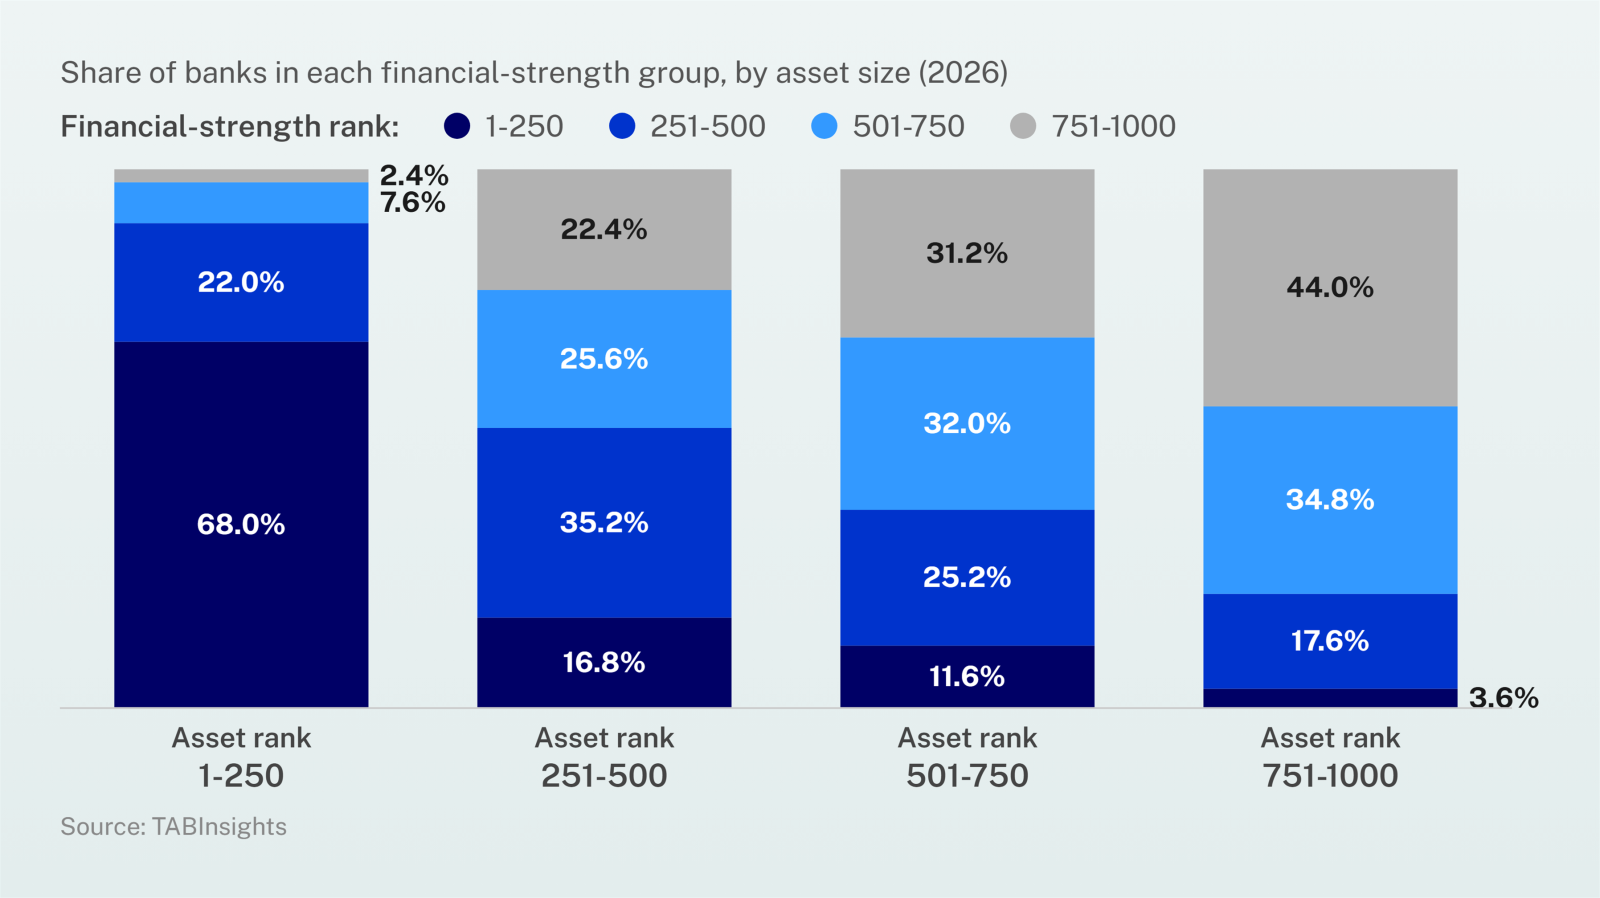
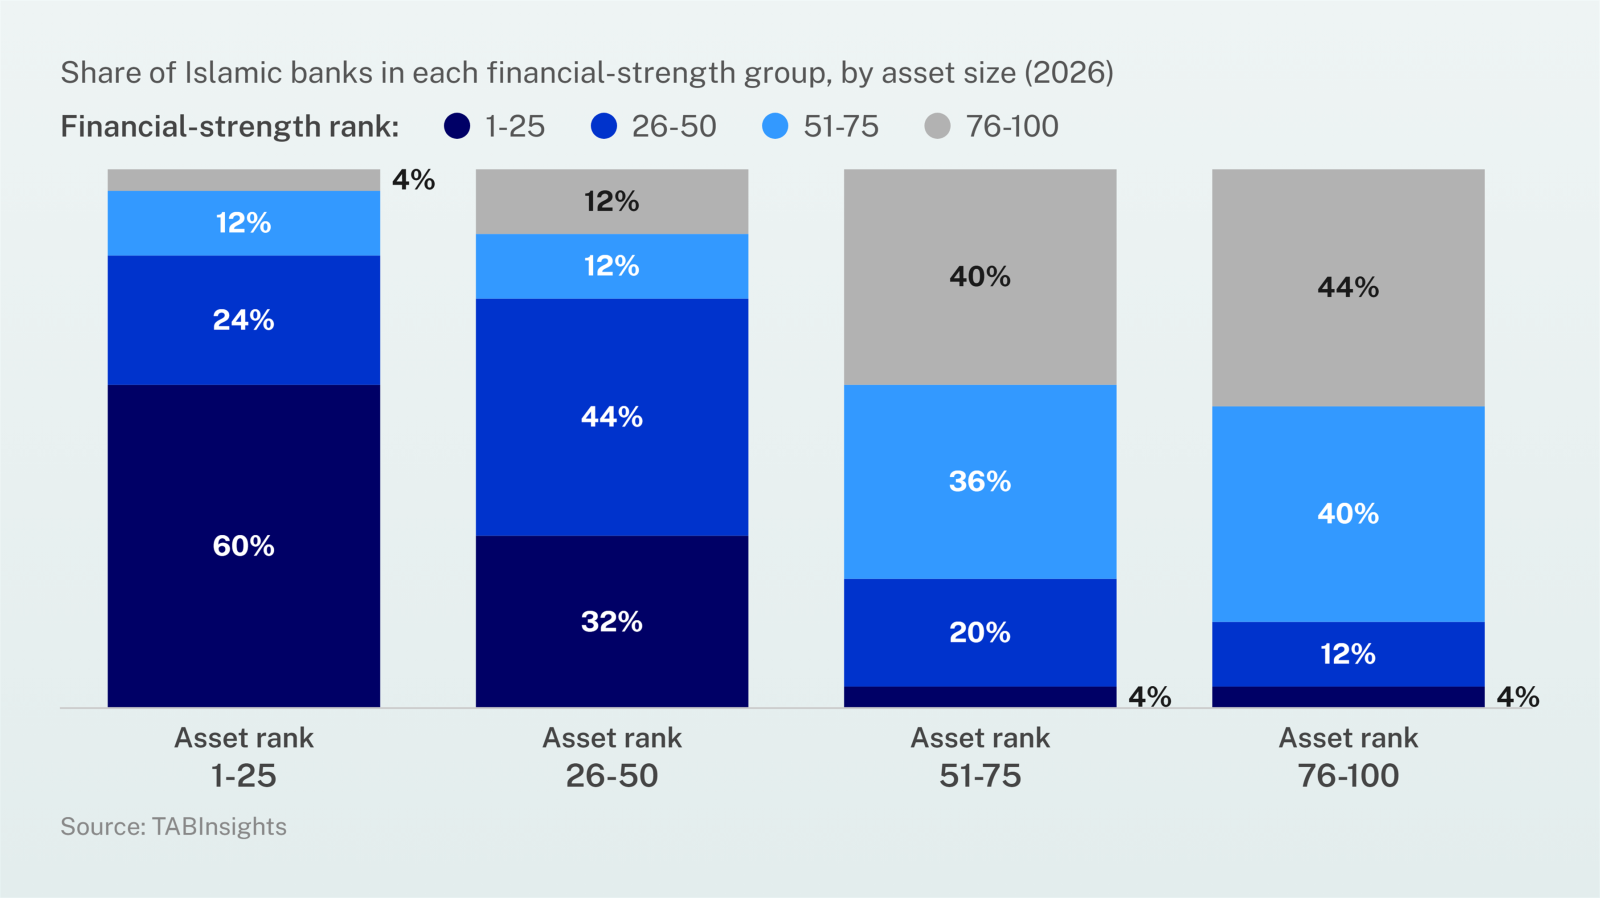
Scale is strongly associated with financial strength, but the TAB Global 1000 World’s Strongest Banks 2026 ranking shows that size is only part of the picture. Some smaller institutions substantially outperform their positions by assets, while exceptional profit growth and increasingly large regulatory liquidity buffers do not necessarily correspond with greater overall strength.

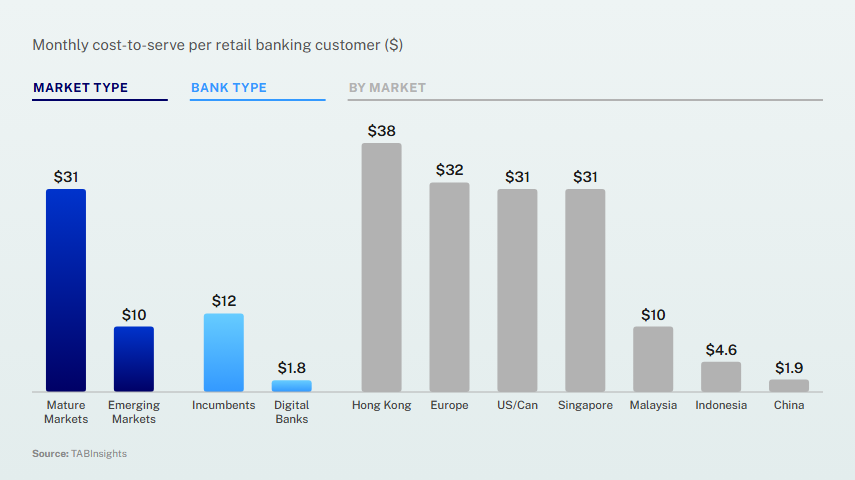
Digital banks serve customers far more cheaply than incumbents, but most generate less revenue for every dollar spent on servicing. Nubank and WeBank stand out, generating 4.1x and 3.8x their servicing cost in revenue respectively, outperforming leading incumbents. Most other digital banks fall short of incumbent benchmarks, showing that lower cost-to-serve alone does not guarantee stronger economics.
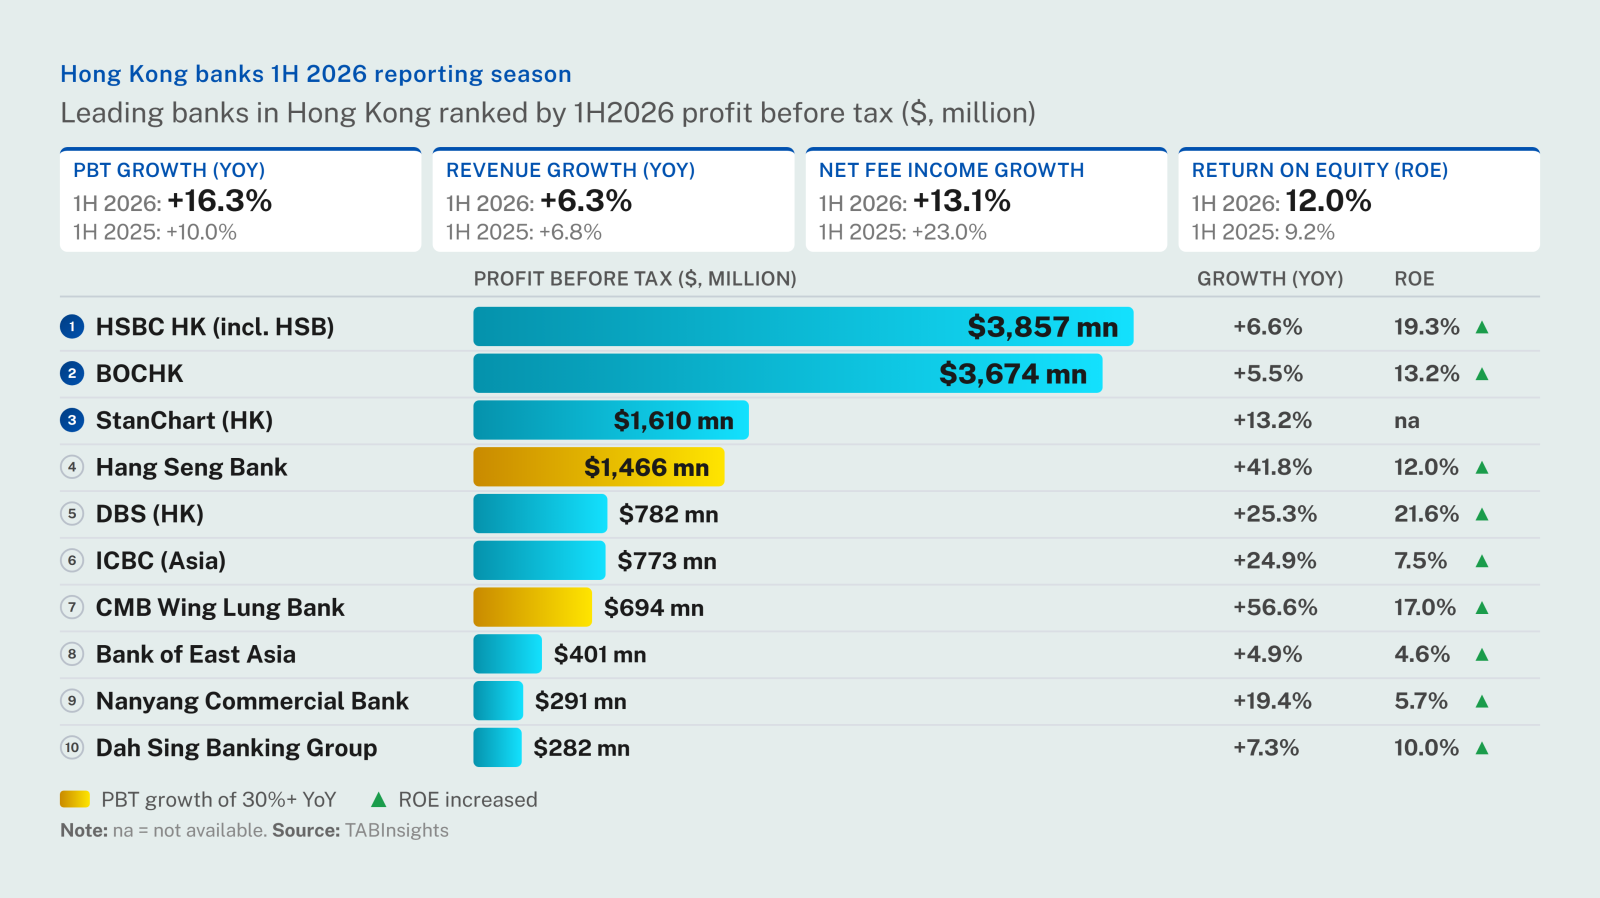
Hong Kong’s leading banks accelerated median pre-tax profit growth to 16.3% year on year (YOY) in the first half of 2026 (1H2026). HSBC Hong Kong (including Hang Seng Bank) continued to lead the large-scale bank segment in earnings scale and returns, while DBS Hong Kong and CMB Wing Lung Bank delivered stronger growth momentum and profitability among mid-sized banks. Across the sector, growth was increasingly supported by fee-based businesses, wealth management, cross-border activity and digitally-enabled customer engagement, which emerged as key drivers of revenue expansion.

Exclusive benefits are on your way. Subscribe and enjoy the benefits.