
Research Notes
Jun 28
The German fintech’s dramatic collapse is likely to reshape the payment processing landscape as market rewards players leading innovation and value creation
The German fintech’s dramatic collapse is likely to reshape the payment processing landscape as market rewards players leading innovation and value creation
Artificial intelligence (AI) is set to transform retail banking, impacting the customer journey from acquisition on through to retention.

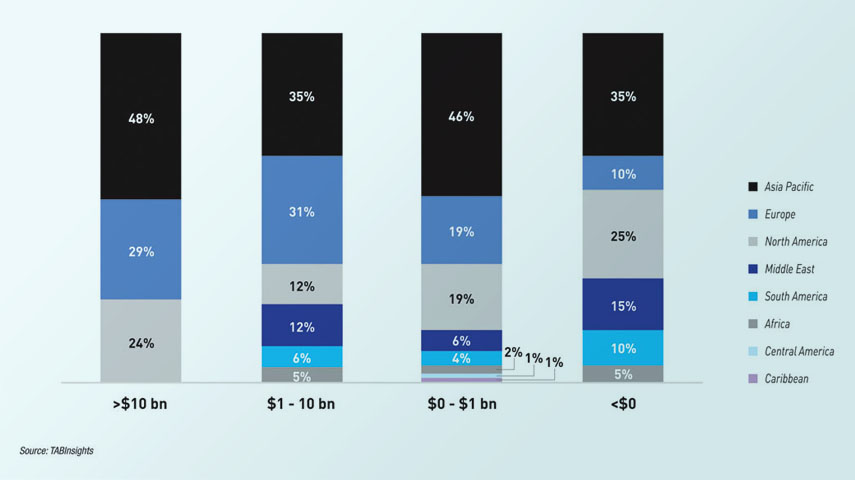
North America demonstrated the highest overall strength, followed by Asia Pacific and the Middle East, with all banks in the ranking averaging decline in return on assets from 0.76% to 0.74%, and improved gross non-performing loan ratio from 1.8% to 1.65%
Chinese banks dominate the world’s top 10 banks by net profit, but their profit growth lagged behind US and UK banks, mainly due to rate cuts, narrowing profit margins.
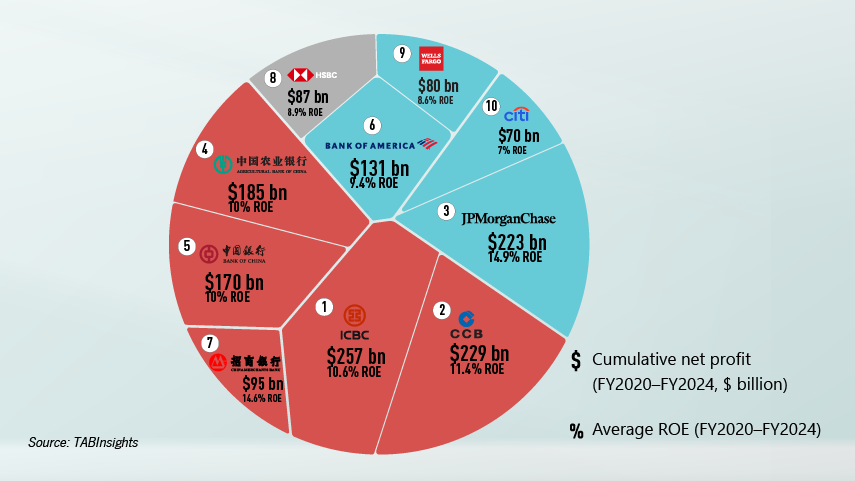
Chinese and US megabanks generate the largest absolute profits through scale and diversification, while emerging-market banks deliver higher — but more volatile — returns on equity.
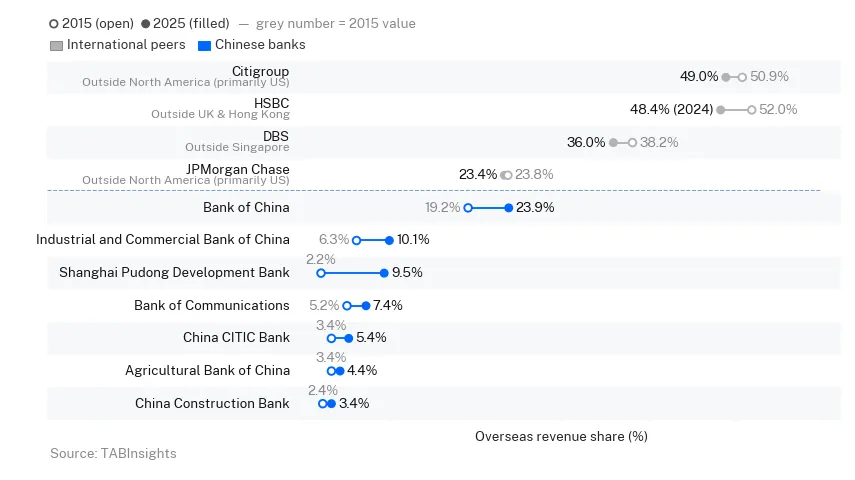
China's major banks are expanding overseas revenue, driven by outbound corporates, renminbi internationalisation and domestic margin pressure. Most earnings, however, remain concentrated in Greater China, highlighting a persistent gap with global peers.
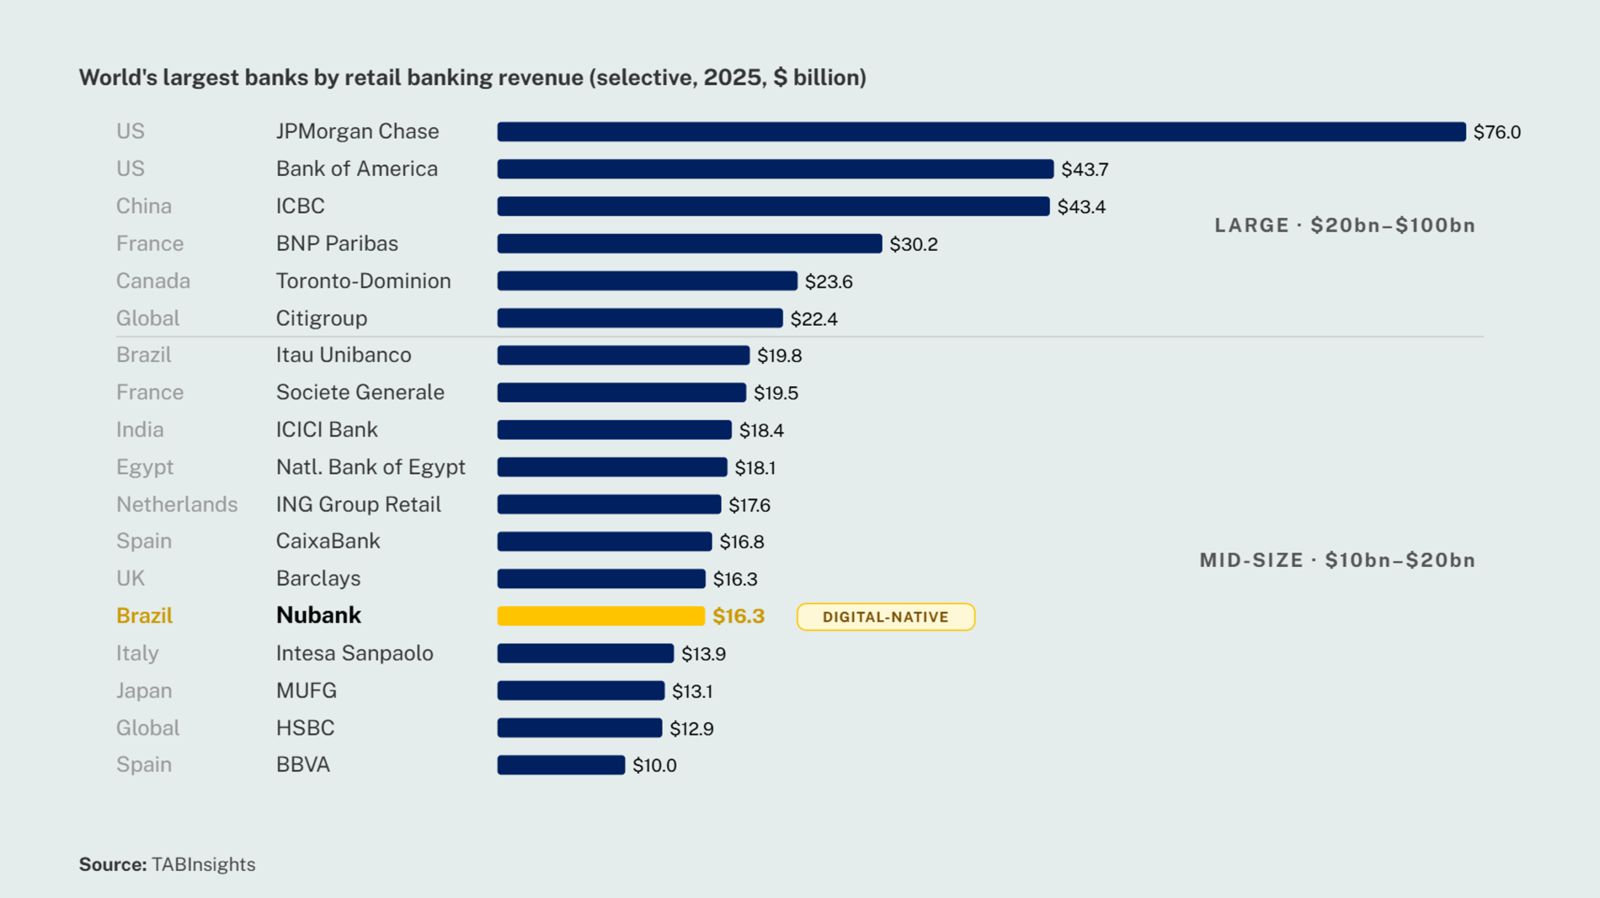
A decade ago, Nubank was a credit card start-up operating out of São Paulo. Today, at $16.3 billion in retail banking revenue (2025), it has surpassed HSBC and Standard Chartered’s global retail banking businesses and is on track to overtake Itaú Unibanco in Brazil in 2026 and Citigroup by 2027. What is emerging is not just rapid growth, but the early stages of a long-term strategy to build a global retail banking franchise.
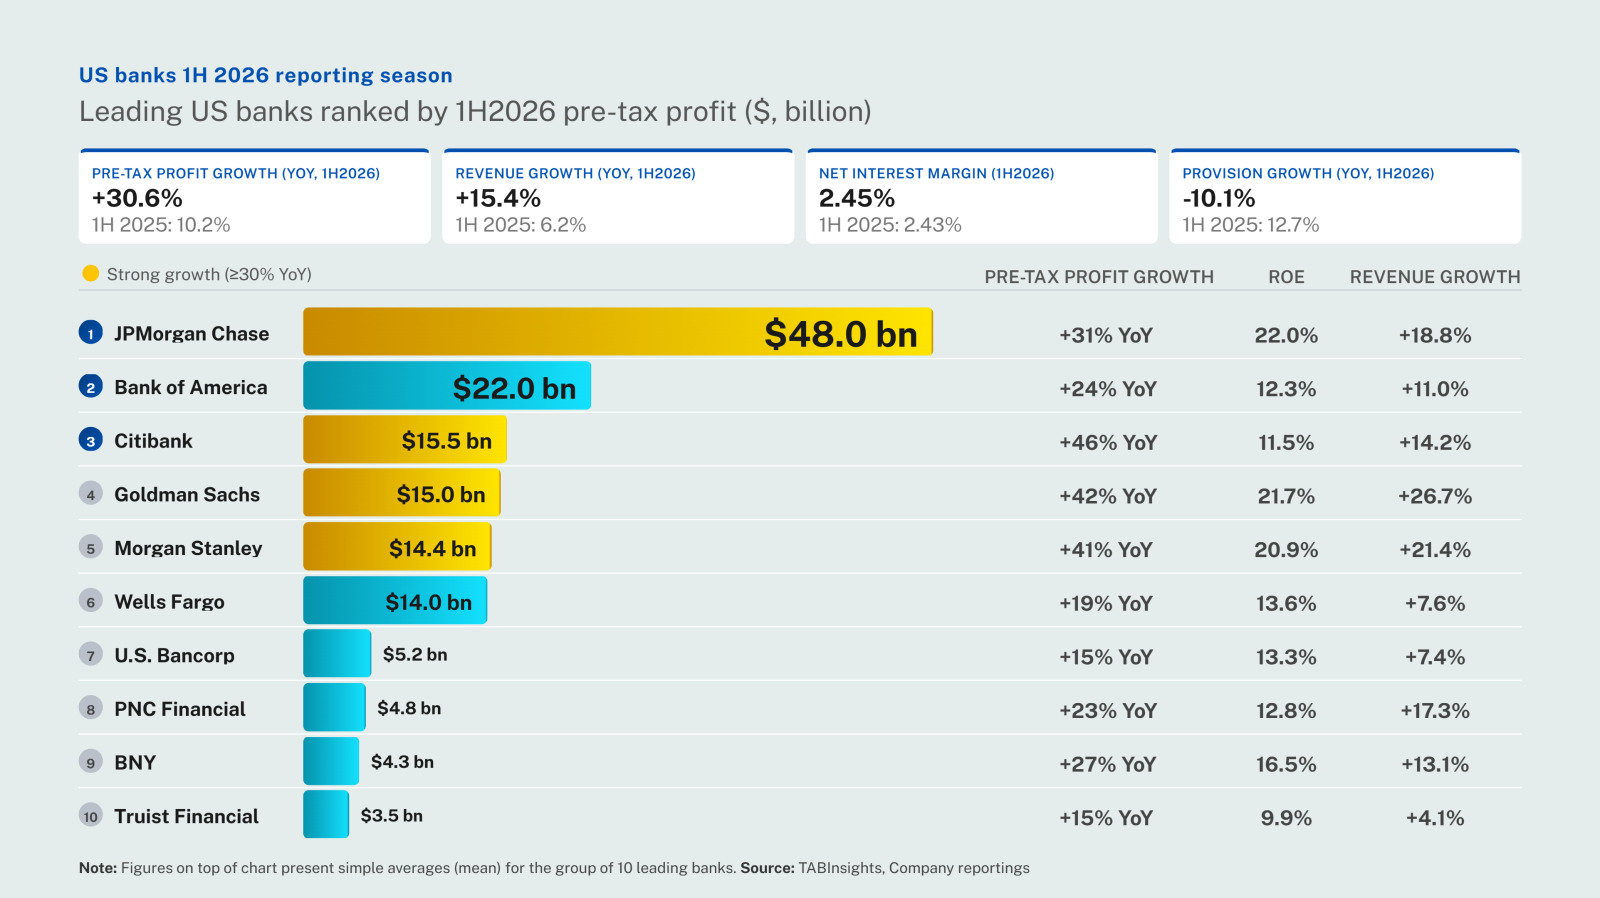
Robust capital markets activity and lower credit provisions lifted first-half earnings at leading US banks, but gains were concentrated among the largest, most diversified institutions. JPMorgan Chase led the group in absolute pre-tax profit, while limited margin expansion and slower revenue growth at regional lenders exposed a widening earnings divide.
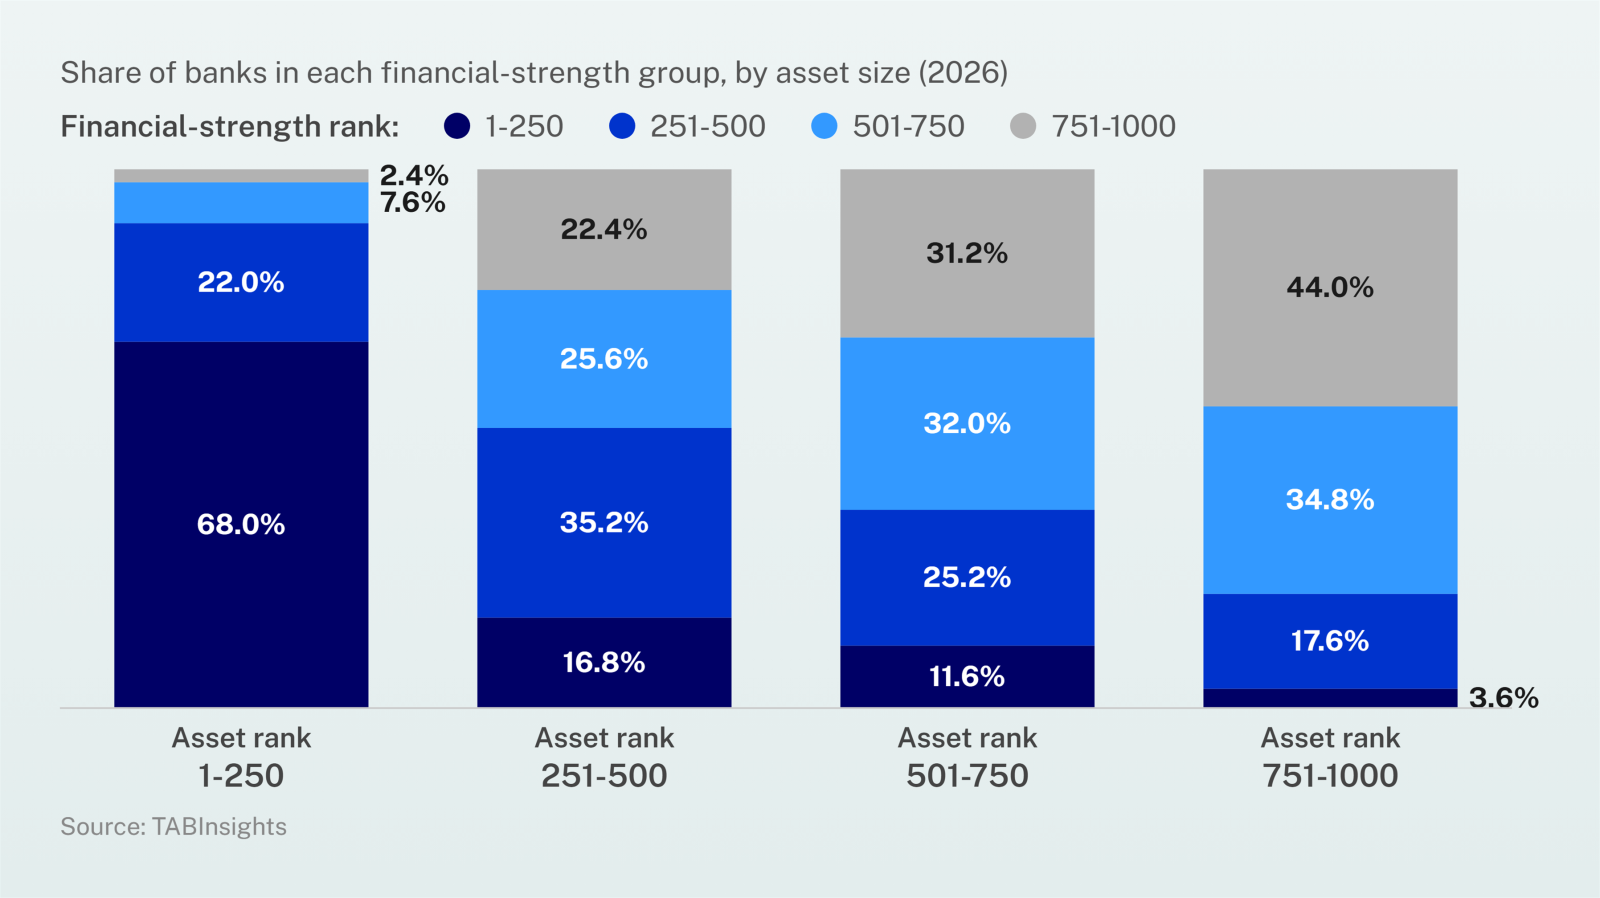
Scale is strongly associated with financial strength, but the TAB Global 1000 World’s Strongest Banks 2026 ranking shows that size is only part of the picture. Some smaller institutions substantially outperform their positions by assets, while exceptional profit growth and increasingly large regulatory liquidity buffers do not necessarily correspond with greater overall strength.
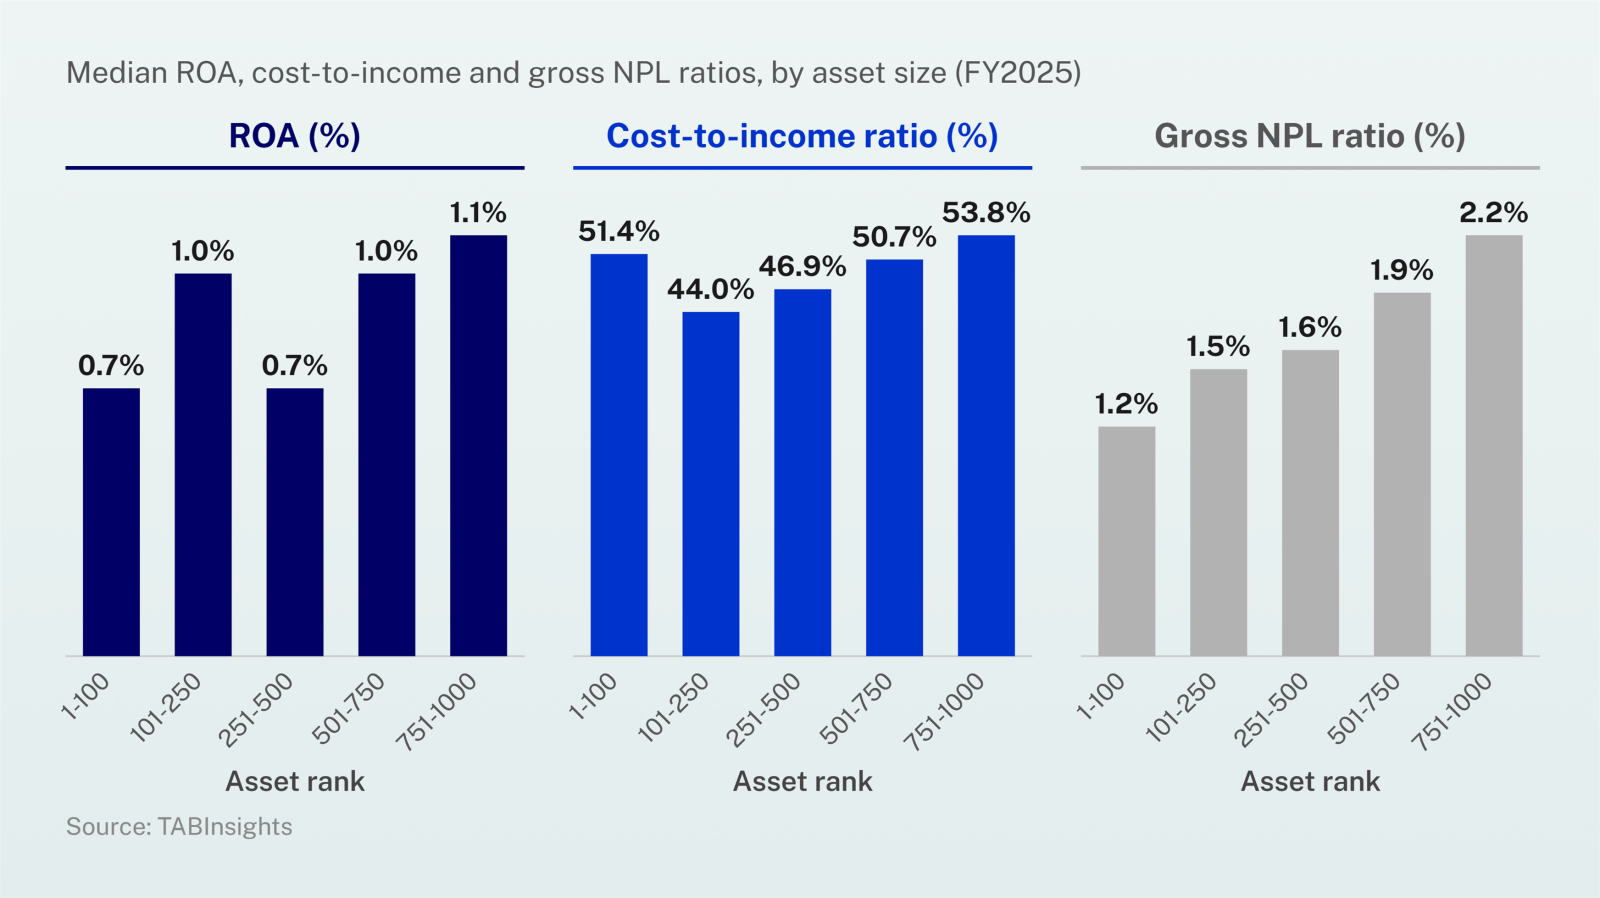
The world’s 1,000 largest banks expanded to $180.7 trillion in assets in FY2025, but cross-tabulation shows that better asset quality is most consistently associated with scale, while greater size does not correspond consistently with faster growth, higher returns or better efficiency.
© Copyright , TABInsights. All Rights Reserved

Mai Kaneko leads international business and marketing at DeCurret DCP, a Japanese fintech firm operating a multi-bank network for tokenized deposit under the DCJPY framework. She oversees international expansion initiatives, bank-fintech partnerships and global go-to-market strategy. She holds a Master’s in International Relations from Georgetown University and a Bachelor’s in Economics from University of Tokyo.
Kinoshita has been involved in product development projects across a wide range of industries in Japan, including e-commerce, retail, banking, insurance, and manufacturing. He joined DeCurret DCP in 2024, where he has been engaged in the development of digital currency infrastructure. In addition to building the underlying infrastructure, he supports digital transformation (DX) initiatives associated with the adoption of digital currency solutions across various industries, and promotes projects aimed at enabling cross-border transactions.
Jason Hunt works within ANZ's Industry & Innovation function, engaging with industry challenges, trends and disruptive technologies across payments, digital assets, platforms and data-driven solutions. ANZ was a participant in Project Acacia, the joint Reserve Bank of Australia (RBA) and Digital Finance Cooperative Research Centre (DFCRC) initiative exploring digital money in wholesale tokenised asset markets, which concluded with its final report in May 2026. ANZ has also previously issued its own Australian dollar-denominated stablecoin, A$DC, to settle a real-money digital asset transaction.
Zhu Kuang Lee leads UOB's Innovation Group, formed in April 2025 to consolidate the bank's work across digital assets, data management, blockchain and enterprise artificial intelligence. He represents UOB in regional digital money and tokenisation initiatives, including collaboration with the Monetary Authority of Singapore (MAS), and has described the bank's approach as embedding compliance into system design from the outset rather than adding it later.
Abhinav is currently based in Singapore and leads Client solutions and Sales for Partior. In this capacity, he oversees clients' journeys including commercial and central banks, from defining use cases to product integration. Before taking on this role, Abhinav gained extensive experience working with both global and local banks. He spearheaded transformative initiatives in Payments and Core Banking, requiring him to coordinate efforts across business units, technology teams, and regulatory bodies. Abhinav played a pivotal role in implementing Faster Payments projects throughout Asia, including notable projects like Singapore G3 Fast, Malaysia Duit Now, and Hong Kong FPS. Prior to his tenure in the banking sector, Abhinav served as a Payments Financial Services consultant to various banks and payment fintech companies such as ANZ, Deutsche Bank, and Bank of America. Originally from India, Abhinav holds an Engineering degree and a Postgraduate qualification in Machine Learning and Artificial Intelligence. He is also a dedicated father of two, and he enjoys spending his weekends playing tennis and cherishing moments with his family.
Sakae Hamasaki joined Sanwa Bank (currently MUFG Bank) in April 1993 and worked in corporate banking across five domestic locations. From 2006 onward, he gained extensive experience in the planning, development, and sales of payment-related services for corporate clients in Japan and overseas. He joined DeCurret DCP in 2022, where he has been leading initiatives to support banks in evaluating the adoption of tokenized deposits, as well as collaborating with overseas partners to build cross-border networks utilizing tokenized deposits.
Anouska Ladds is Executive Vice President of Commercial & New Payment Flows, Asia Pacific at Mastercard, based in Singapore. With over 17 years at Mastercard, she has held senior roles across sales, strategy, operations, market development, consultancy, and product development, spanning Asia Pacific, Europe, the Middle East, and Africa. Previously at Barclaycard, she specialised in strategy, customer experience, communications, and SME/acquiring businesses.
David is a seasoned technology executive with significant experience and has over 25 years' experience in CISO and CIO roles across different industries and countries. David has served as a CIO spans across multiple industries and geographies. He was winner Australia CIO of the Year for driving CUA's Transformation. Also, David was CISO for HSBC and Global Head Technology, Cyber and Data Risk Macquarie Group.
A regular conference keynote speaker and thought leader he writes for CIO, CSO, Computerworld and Australian Institute of Company Directors (AICD). His best-selling book - the Aspiring CIO & CISO was published in June 2024 and his second book A Day in the Life of a CISO launched in October 2025 and is already best seller in UK, Singapore, Japan and Australia.
Johnson is a seasoned executive and data and AI leader with over 15 years of experience across the public and private sectors. He is currently Assistant Chief Executive at IMDA, where he helps shape Singapore’s digital future and advance the digital economy. He has held senior data and AI roles in regional banking and global consulting, and began his career in defence and critical infrastructure.
A distinguished leader who has spent over two decades shaping the future of technology and digital finance. Barani Sundaram has held senior leadership positions across Dubai, Singapore, Malaysia, India, and Vietnam, building an impressive track record of delivering large-scale technology transformations across diverse and dynamic markets. As Chief Technology Officer of EastWest Bank in the Philippines, Barani has been instrumental in modernizing the bank's core technology infrastructure, elevating its cybersecurity posture, and championing the adoption of Artificial Intelligence and machine learning. Under his leadership, EastWest Bank has harnessed AI to enhance customer experiences, strengthen fraud detection, and enable data-driven decision-making — while ensuring the highest standards of cyber resilience and regulatory compliance. His strategic vision, technical expertise, and ability to navigate complex challenges have earned him recognition as a pivotal force in shaping intelligent and secure digital banking in the Philippines.
Daniele Tonella is Chief Technology Officer (CTO) and member of the Management Board Banking since August 2024. Daniele is responsible for overseeing and managing the total IT landscape and advising on technology-driven business opportunities. Daniele is a member of the Tech Advisory Board of The Hg Foundation. He holds an engineering MSc from the Swiss Federal Institute of Technology in Zurich (ETHZ) and completed various executive education programmes at Harvard, IMD, INSEAD and MIT Sloan.
Virag Masuraha is a seasoned executive with over 25 years of experience leading Fraud, Financial Crime, and Risk functions for top U.S. financial institutions. He is widely recognized for driving strategic initiatives that reduce costs, enhance profitability, and enable sustainable growth, while successfully managing complex regulatory engagements.
Currently, Virag serves as Managing Director of US AML Financial Crime Modeling at Bank of America. Prior to this role, he held leadership positions at Citi and PNC, where he spearheaded global fraud and anti-money laundering (AML) analytics and modeling functions.
With deep expertise in financial crime and fraud data, analytics, and modeling, Virag has led enterprise-wide strategies in advanced analytics—including big data, AI/ML, entity linkages, network analysis, and machine learning—alongside cyber and digital fraud prevention across consumer and commercial portfolios.
Virag holds an MBA from the Kellogg School of Management and a Master’s in Engineering from Vanderbilt University.
Jackson Oh is the Chief Technology Officer at ANEXT Bank, where he leads the bank’s technology strategy, architecture, and engineering execution as ANEXT scales its digital banking platform for local SMEs and foreign business owners in Singapore.
With close to two decades of experience across banking, fintech, and enterprise technology, Jackson brings a rare blend of deep financial services expertise and hands-on product and platform leadership. Prior to ANEXT Bank, he served as Chief Product Officer at Tribe Fintech and held senior technology and product leadership roles at 360F, SunGard (now part of FIS), AirWatch by VMware, Samsung Electronics, and Bank of America.
Jackson has led large-scale, cloud-native platforms across corporate banking, payments, capital markets, and SaaS environments. He is passionate about building resilient, scalable financial infrastructure, and enabling innovation while meeting the realities of regulatory and operational complexity.

 Google
 LinkedIn